
Cash-Out Refinance on a Free-and-Clear Investment Property in Washington, DC
Yes, you can take cash out of a DC rental or investment property you own free and clear, in any of the District’s eight wards. If it’s vacant or not yet rented, a bridge cash-out goes up to 60–65% of value, with an inspection instead of an appraisal, no minimum FICO and no tax returns. If it’s rented, a DSCR cash-out goes up to 70% of the appraised value and qualifies on the rent, with no tax returns, W-2s or debt-to-income ratio. Written approval in 24 hours from a direct lender using its own capital, lending since 2007.
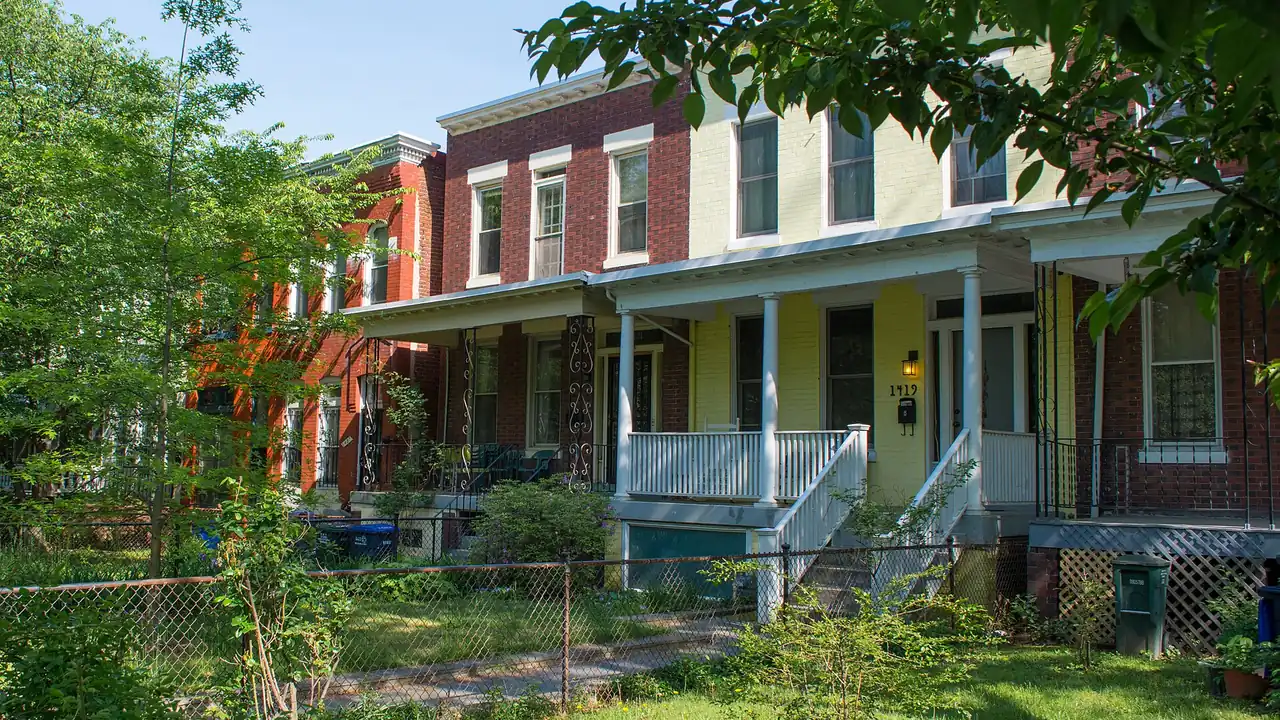
Photo: Tim Evanson, CC BY-SA 2.0, cropped

A Free-and-Clear Cash-Out We Closed Next Door
Can a property with no mortgage, and sometimes no tenant, be refinanced for cash? Yes. Here is one we funded just across the DC line in Hyattsville, Maryland.
- Closed in
- 7 days
- Property
- Vacant, owned free and clear
- Underwritten on
- Property value
The owner held the property free and clear, and it was sitting vacant. We lent on the property’s value and closed the cash-out refinance in 7 days.
Details limited to protect borrower privacy. See all recently funded loans.
Vacant or Rented: Which Cash-Out Fits
Both are business-purpose loans on non-owner-occupied investment property. The difference is whether the property has rent to qualify on.
Vacant or not rented: bridge cash-out
Sized on the property’s value and your exit, not on rent.
- Up to 60–65% of the property’s value, with a clear exit
- Loans from $50,000 to $2M; larger loans case by case
- Rates from 10.49% to 12.99%, subject to underwriting. Points are quoted per deal on the written term sheet
- No appraisal: we inspect the property instead
- No minimum FICO. No tax returns and no debt-to-income ratio
- No prepayment penalty; a 3-month minimum interest applies
- Clean residential files close in as little as 3 business days
Rented: DSCR cash-out
A long-term rental loan that qualifies on the property’s rent.
- Up to 70% of the appraised value on a cash-out
- Qualifies on the rent, with no tax returns, W-2s or debt-to-income ratio
- Loans up to $3M
- An appraisal is required
- Credit score of 640+ on most programs
- Clean files close in about 14 to 21 days
The two paths work together
Take a bridge cash-out on the vacant property now, put a tenant in, then refinance into our DSCR rental loan once it is rented. Selling the property also pays off the bridge loan.
From First Call to Cash in Hand
The people who approve your loan are the people who fund it, so there is no outside lender to wait on.
1. Send the property
Tell us the address, whether it is vacant or rented, and how much cash you want to take out.
2. Written approval in 24 hours
You get a written approval within 24 hours, so you know where you stand before you spend anything on the deal.
3. Inspection or appraisal
On a bridge cash-out we inspect the property; there is no appraisal. A DSCR cash-out uses an appraisal.
4. Close
Clean bridge files can close in as little as 3 business days. DSCR cash-outs take about 14 to 21 days.
How Much Cash Can You Pull Out?
Here is what our maximum leverage looks like on a DC investment property worth $600,000 and owned free and clear.
- Property value
- $600,000, owned free and clear
- Bridge cash-out at 60%
- $360,000
- Bridge cash-out at 65%
- $390,000
- DSCR cash-out at 70%
- $420,000
Illustrative only, using our maximum ratios. Not a real deal and not a quote. Amounts are before closing costs, and every loan is subject to underwriting. The bridge value comes from our own inspection and valuation; the DSCR value comes from the appraisal.
DC Rules That Affect a Free-and-Clear Property
Business-purpose loans on non-owner-occupied investment property only. We never lend on a home you or a family member live in or plan to live in.
Vacant property is taxed higher
DC taxes most residential property at $0.85 per $100 of assessed value, but property classified as vacant at $5.00 and blighted property at $10.00 per $100. The Department of Buildings decides the vacant and blighted classifications, so an empty house can get expensive to hold.
Renting it out? License it first
Renting a single-family home, townhouse or condo unit in DC takes a Basic Business License with a one-family rental endorsement from the Department of Licensing and Consumer Protection, after an inspection, and registration with DHCD once the license is issued.
All eight wards
We lend across all eight wards of the District, from rowhouses on Capitol Hill and in Petworth to the neighborhoods east of the Anacostia River.
DC hard money loans →General information, not legal or tax advice. Confirm with the DC Office of Tax and Revenue and DLCP.
Where We Make Cash-Out Loans
We lend throughout the Washington DC metro area: Washington DC, Maryland and Northern Virginia. Surrounding neighborhoods are considered case by case.
What to Send Us
- The property address and your estimate of its value
- Whether it is vacant or rented, and the lease and rent if it is rented
- How much cash you want to take out and what it is for
- Your exit: refinance into a rental loan, or sell
- The name you hold title in, personally or through an LLC
Related: bridge loans, DSCR rental loans, loans with no appraisal and inherited-property loans.
DC Free-and-Clear Cash-Out Questions
Can I get a cash-out refinance on a vacant property I own free and clear in DC?
How much cash can I pull out of a free-and-clear DC property?
What do you qualify the loan on?
Is there an appraisal?
How fast can you close?
My DC property is vacant. Does that change the property tax?
Can I use this loan on a home I or a family member live in?
I inherited a DC house that's free and clear. Can I take cash out?
Own a DC Property Free and Clear?
Tell us whether it’s vacant or rented and how much you want to take out. Written approval within 24 hours.